Barclays US

Screenshots
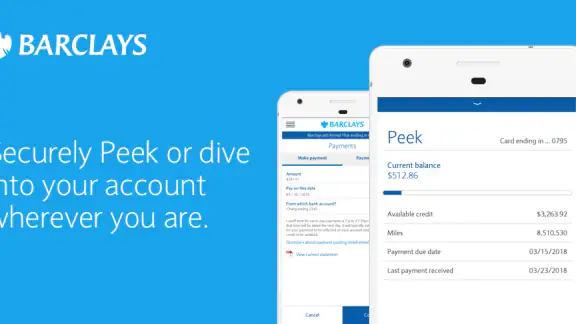
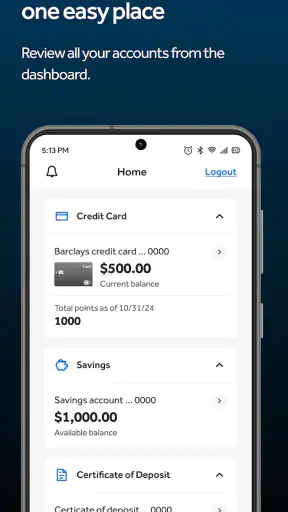
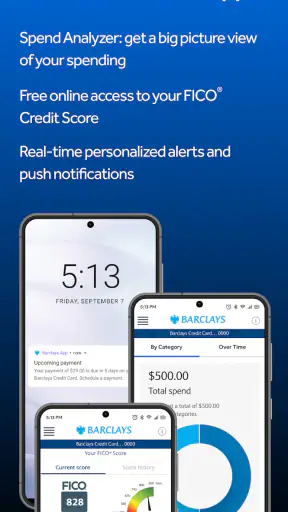
Details
- Rating
- 7.15K reviews
- Version
- 8.7.2
- Developer
- Barclays US
Analysis by Norviv
Managing money from a phone is most useful when it works at the exact moment I need it: before a purchase, while checking a payment, or when I am trying to understand why my available balance changed. Barclays US is a free finance app from Barclays US that puts those everyday banking moments into a mobile interface. I found its strongest quality to be convenience rather than spectacle. It is designed for customers who already use Barclays US services and want a practical way to stay connected to their accounts while moving through a normal day.
The app has been available since February 16, 2012, and its current version is 8.7.2. Its store presence shows a 4.6 average from around 60 thousand ratings, with more than 1 million installs. Those figures suggest that it has become a familiar tool for a substantial number of users, but popularity does not remove the need to judge how it behaves in real mobile situations. For me, the important question is not whether a banking app looks polished in ideal conditions. It is whether I can use it clearly and safely when the connection is weak, the screen is small, or I need an answer quickly.
How Barclays US feels when connectivity matters
When connectivity matters, I treat a banking session as a handoff between my phone, the network, and the account information I need—not as a guaranteed instant result. I’ll focus on how to distinguish a slow response from a completed action, and on the practical choices that help keep a quick check from turning into guesswork. That distinction is especially useful when I’m away from a dependable connection.
The app is most valuable when the network is available
A finance app depends heavily on communication with its banking service. When I open Barclays US to check an account, review a transaction, or handle a payment-related task, I expect current information rather than a static snapshot. That makes the quality of the connection part of the experience. On a reliable Wi-Fi or mobile-data connection, the app fits naturally into short checks throughout the day. I can use it as a quick point of contact instead of waiting until I reach a computer.
This network dependence is easy to overlook because the interface itself may feel simple. The difficult work happens behind the screen: the app needs to reach the service, authenticate the session, and present information that I can trust. If the connection is delayed, the experience changes from a quick glance into a waiting exercise. That is not a flaw unique to Barclays US, but it matters more in finance than in many other categories because I am usually checking information that affects a decision.
A realistic example is standing at a checkout and wondering whether a recent payment has already affected my available funds. With a stable connection, opening the app can be more useful than guessing or searching through old notifications. If the store has poor reception, however, I would not treat a delayed screen as proof that nothing has happened. My practical rule is simple: never make a financial decision based on a screen that has not clearly refreshed.
Short mobile sessions suit the design
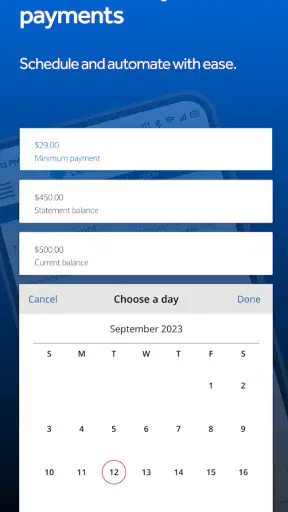
Barclays US makes the most sense for brief, purposeful sessions. I would open it to check recent activity, confirm that a payment appears as expected, or review an account before making a purchase. This kind of use is more comfortable on a phone than signing into a desktop site, especially when I am away from home. The app’s value comes from reducing the distance between a question and the account information that can answer it.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
That convenience also creates a temptation to check repeatedly. A phone makes financial information feel constantly available, but repeated refreshing is not a substitute for understanding transaction timing. Some activity may take time to appear or settle, and a network delay can make that timing seem even more confusing. I prefer to use the app for a deliberate check, then give the information enough context before acting.
The mobile format is particularly helpful for people who divide their financial tasks into small moments. I can check an account during a commute, look at activity before paying a bill, or review a purchase after leaving a shop. Those situations are exactly where a dedicated application is more convenient than a browser tab. On the other hand, anyone who regularly needs a wide view of many records at once may still prefer a computer, where longer financial reviews are easier to organize.
What happens when the connection is weak
The main friction appears when the network is unreliable. A banking app cannot provide much reassurance if the latest account information has not reached the phone. In a basement, crowded venue, rural area, or train with changing reception, loading may take longer than expected. I would rather see a clear indication that the app is still trying than assume an incomplete view is current, but users should remain cautious whenever a screen takes unusually long to respond.
This is also where the difference between an app and a conventional website becomes less dramatic. A mobile app is convenient to open, but it still needs a working path to the banking service for current information. If I am choosing between Barclays US and a browser, I would not choose the app because I expect it to overcome a missing connection. I would choose it because its mobile workflow is more direct for routine account checks.
For important actions, I recommend waiting until the connection is stable rather than repeatedly tapping buttons. Repeated attempts can make it harder to tell whether a request went through, especially when the screen responds slowly. A better habit is to pause, look for a visible result, and then verify the relevant activity before trying again. This is one of the most useful adjustments I made while judging the app: patience is part of safe mobile banking.
Recovery matters more than speed
When an app session is interrupted, the recovery experience becomes important. A dropped connection, a switch between Wi-Fi and mobile data, or a long pause can leave me unsure whether I am looking at a current screen. I treat any interrupted session as unfinished until the app reconnects and displays the information again. That approach may feel cautious, but it avoids turning a technical delay into a financial mistake.
My preferred recovery routine is to stop interacting, confirm that the phone has a usable connection, and reopen or reload the relevant view only when necessary. I avoid submitting the same request several times simply because the first response is slow. If the result remains unclear, I move to a more dependable connection and check the account again. The app is useful here as a source of confirmation, but it cannot replace careful judgment about whether an action actually completed.
This is a limitation worth stating plainly: the app cannot make every network problem disappear. Users who expect uninterrupted access in poor-signal locations may find the experience frustrating. The better fit is someone who understands that mobile banking combines a convenient interface with a live service connection. Barclays US handles the everyday side of that relationship well enough for routine use, but I would not depend on it as my only option during a connectivity emergency.
Using mobile data without wasting attention
For data-conscious users, the sensible approach is to use Barclays US for targeted checks instead of leaving it open while doing unrelated tasks. A quick account review usually makes more sense than repeatedly refreshing the same screen. I also prefer to check important information when I have a stable connection, because a failed attempt can waste both time and data without giving me a reliable answer.
This is not an app I would describe as entertainment that runs in the background. Its purpose is transactional and informational, so opening it only when I have a financial reason to do so is the natural workflow. That makes it easier to control attention as well as connectivity. I can decide what I need to verify, open the app, complete the check, and close it instead of turning financial monitoring into constant phone activity.
People with limited mobile data should be especially careful in places where reception keeps changing. A weak signal can lead to repeated loading attempts, and those attempts are not useful if the information still cannot be confirmed. Wi-Fi is the better choice for longer account reviews, while mobile data is perfectly practical for a short check when the signal is dependable. The key trade-off is convenience versus certainty: speed is helpful, but current and clearly displayed information matters more.
Everyday workflows where it earns its place
I see three strong everyday uses. The first is a pre-purchase check, when I want to understand my position before committing to a larger expense. The second is post-purchase verification, when I want to make sure a transaction appears in the expected place. The third is routine monitoring, where a short session helps me notice activity without waiting for a monthly review. These uses are simple, but they are exactly the tasks a phone-based finance app should make easier.
A less obvious benefit is the discipline created by checking at the right moments. Instead of trying to reconstruct spending from memory, I can look soon after an important purchase and connect the activity with the real-world event. That can make account review more understandable, particularly for people who find a long list of transactions difficult to interpret later. The app does not replace a personal budget or financial plan, but it can make the information needed for those plans easier to reach.
There is a trade-off in using a small screen for financial detail. A phone is excellent for a quick answer, but less comfortable for comparing many entries or thinking through a complicated month. I would use Barclays US for immediate awareness and a larger screen for deeper review when possible. That division of labor is more realistic than expecting a mobile app to be equally good at every banking task.
Who should use it and who may prefer something else
Barclays US is a good match for an existing Barclays US customer who wants a convenient mobile route to routine financial information. It is also suitable for someone who values short, focused checks and is comfortable using a network-connected service. The free price removes a direct cost barrier, and the Everyone age rating makes it broadly approachable from a store perspective.
I would be more hesitant to recommend it to someone who does not already use Barclays US services, because a banking app is most useful when it connects to the accounts and services a person actually needs. It is also not my first choice for someone whose priority is offline access, since current financial information depends on communication with the service. A person who mainly wants advanced budgeting across several institutions may find a dedicated budgeting tool more suitable, while someone who prefers extensive desktop-style account management may be happier with a browser or computer.
Compared with using a normal mobile browser, the app feels more purpose-built for repeated phone access. Compared with a general budgeting application, its advantage is directness rather than broad financial aggregation. Compared with visiting a branch or waiting to use a desktop, it is clearly more convenient for quick checks. None of those alternatives is universally better; the right choice depends on whether the user values direct mobile access, broader planning tools, or a larger workspace.
Practical habits for safer, clearer sessions
I would begin by opening the app only when I know what I want to check. That small step reduces aimless browsing and makes it easier to notice whether the information shown answers the question. When the network is unstable, I would avoid repeating an action and instead wait for a dependable connection. After a delayed session, I would verify the final result rather than relying on the fact that a button appeared to respond.
I would also separate urgent checks from detailed reviews. If I am about to make a purchase, I need a concise and current view. If I am reviewing several transactions or trying to understand a spending pattern, I would choose a calmer setting with stronger connectivity and more screen space. This workflow makes the app feel less frustrating because it respects what a phone does well and what it does not.
Finally, I would keep expectations realistic. The app is a convenient access point, not a guarantee that every network, transaction update, or mobile session will be immediate. Its usefulness comes from combining quick access with sensible user habits. In finance, knowing when not to proceed is just as important as knowing how to open the app.
My connectivity verdict
After using Barclays US as a mobile finance tool, I see it as a practical companion for customers who want quick, connected access to their Barclays US accounts. Its strongest moments happen on a stable network, when a short session can answer an everyday question without the ceremony of a desktop visit. Its weak point is the same one shared by most live banking services: poor connectivity turns a simple task into an uncertain one.
The app’s 4.6 average and more than 1 million installs indicate that many people have made it part of their mobile routine, but my recommendation is based on fit rather than popularity. I would recommend it to Barclays US customers who want convenience, understand the importance of confirming that information is current, and mainly perform focused checks. I would look elsewhere for offline-first access, cross-bank budgeting, or extensive financial analysis.
My final view is that Barclays US works best when treated as a connected financial checkpoint, not as a replacement for every banking channel. Used with a reliable connection and a little patience during interruptions, it makes ordinary account awareness easier. Used in a weak-signal location or with repeated taps and guesses, it can create more uncertainty than it solves. That honest balance is what makes the app worthwhile for the right user.
As a free finance app developed by Barclays US, it offers a straightforward reason to keep it on a phone: access to routine banking tasks in the places where people actually make spending decisions. The experience is not about flashy extras. It is about having a familiar route to financial information, knowing when connectivity is affecting the result, and choosing the safer next step when the screen does not tell the whole story.
Frequently Asked Questions
01What is Barclays US, and what can I use the app for?
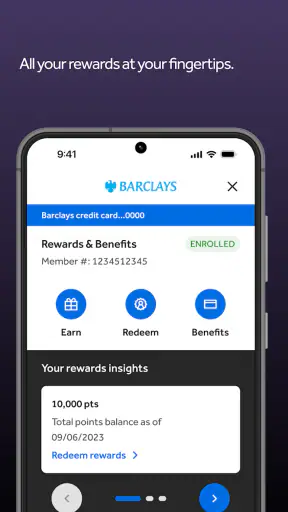
Barclays US is the official mobile banking app for managing eligible Barclays products, such as credit cards and certain savings or lending accounts, depending on your customer profile. After signing in, you can typically review balances, check transactions, make payments, manage account details, view statements, and receive account notifications. Available features may vary by product and region.
02Is the Barclays US app safe to use for mobile banking?
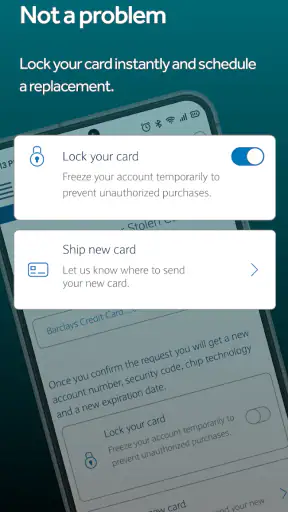
The Barclays US app includes standard security features designed to protect your account, such as secure sign-in, device verification, encryption, and transaction monitoring. You should still use the app only on a trusted device, keep your operating system updated, avoid public Wi-Fi for sensitive activity, and never share passwords or one-time security codes. Download it only from an official app store.
03Can I make payments and manage my Barclays account through the app?
In most cases, the app allows eligible customers to make payments, review payment history, check due dates, and manage account information without visiting a website. Some payment options, transfer capabilities, or account-management tools may depend on the specific Barclays product you hold. Always confirm payment details and allow enough processing time before a deadline.
04Does Barclays US charge fees for using the mobile app?
Downloading and using the Barclays US mobile app is generally not charged as a separate app-access fee, but normal account terms still apply. Depending on your product, you could encounter interest, late-payment charges, balance-transfer fees, foreign transaction fees, or other service costs. Your mobile carrier may also charge data fees, so review your account agreement and wireless plan.
05What should I do if I cannot log in to Barclays US or notice suspicious activity?
If you cannot access the app, first check your internet connection, confirm that the app is updated, and use the official password or username recovery options rather than repeatedly guessing your credentials. If you notice an unfamiliar transaction, receive a suspicious message, or believe your account is compromised, contact Barclays through the verified support number or secure in-app channels immediately.


